
NFT & Virtual Asset Distribution Structure: Legal and Tax Advisory
사건 개요
- Client Information
- Corporate / Business Entity
- Case Details
-
Decent Law Firm's Virtual Asset Practice represented a company operating in the Web3 ecosystem — providing planning, branding, distribution, and monetization consulting for creators' original works through virtual asset-based structures.
The firm provided comprehensive legal and tax advisory on the distribution of NFT auction proceeds and the appropriate tax treatment of those funds.
The client had received NFT auction proceeds in stablecoins through an overseas auction platform and recognized that distributing those funds between the creator and the company carried significant legal and tax risk. They engaged Decent for structured guidance.
A further complication: under current Korean regulations, it remains practically difficult for general for-profit corporations to open a corporate real-name account at a domestic exchange for virtual asset transactions. Access is being permitted only in limited, phased stages in line with the financial regulator's roadmap — making legally compliant operational structures an urgent priority.
디센트 전략
We conducted a comparative analysis of multiple proposed distribution routes, examining risks including piercing of the corporate veil, whether arrangements could be characterized as nominee accounts, and the potential for double taxation.
We identified that routing proceeds through a domestic exchange account carried a significant risk of revenue being attributed directly to the representative as an individual, due to the real-name account linkage requirement. We assessed that structures utilizing overseas exchanges or cold wallets were comparatively more defensible from a fund traceability standpoint.
✔️ Escrow Structure Design and Documentation Framework
To establish that the representative's personal wallet was acting as a temporary custodian of corporate funds — not a personal recipient — we designed a practical documentation framework. This included an escrow agreement, internal board approval records, and settlement statements to minimize legal exposure.
We specified the essential contractual elements: wallet address identification, distribution conditions and timelines, and clear language emphasizing the custodial nature of the arrangement.
This created a defensible basis for demonstrating that the representative's wallet functioned as an escrow account temporarily holding corporate funds — providing a solid foundation for explaining fund attribution and use in the event of a tax audit or civil or criminal dispute.
✔️ Virtual Asset Tax Treatment Guidelines
We established the date of stablecoin receipt as the revenue recognition date, and provided immediately applicable tax guidelines covering: KRW conversion methodology based on exchange rates at the time of deposit, VAT filing treatment, classification of staking income as non-operating revenue, and the recognition of foreign exchange gains upon liquidation.
✔️ Documentation Requirements by Creator Type
We categorized creators into domestic resident individuals (non-business), individual or corporate business operators, and non-residents or foreign corporations — and clarified the applicable tax invoice and receipt issuance requirements and withholding obligations for each category.
By characterizing the legal nature of the auction proceeds as consideration for asset transfer, we advised on the specific contractual language needed to avoid triggering withholding tax obligations.
결과 및 의의
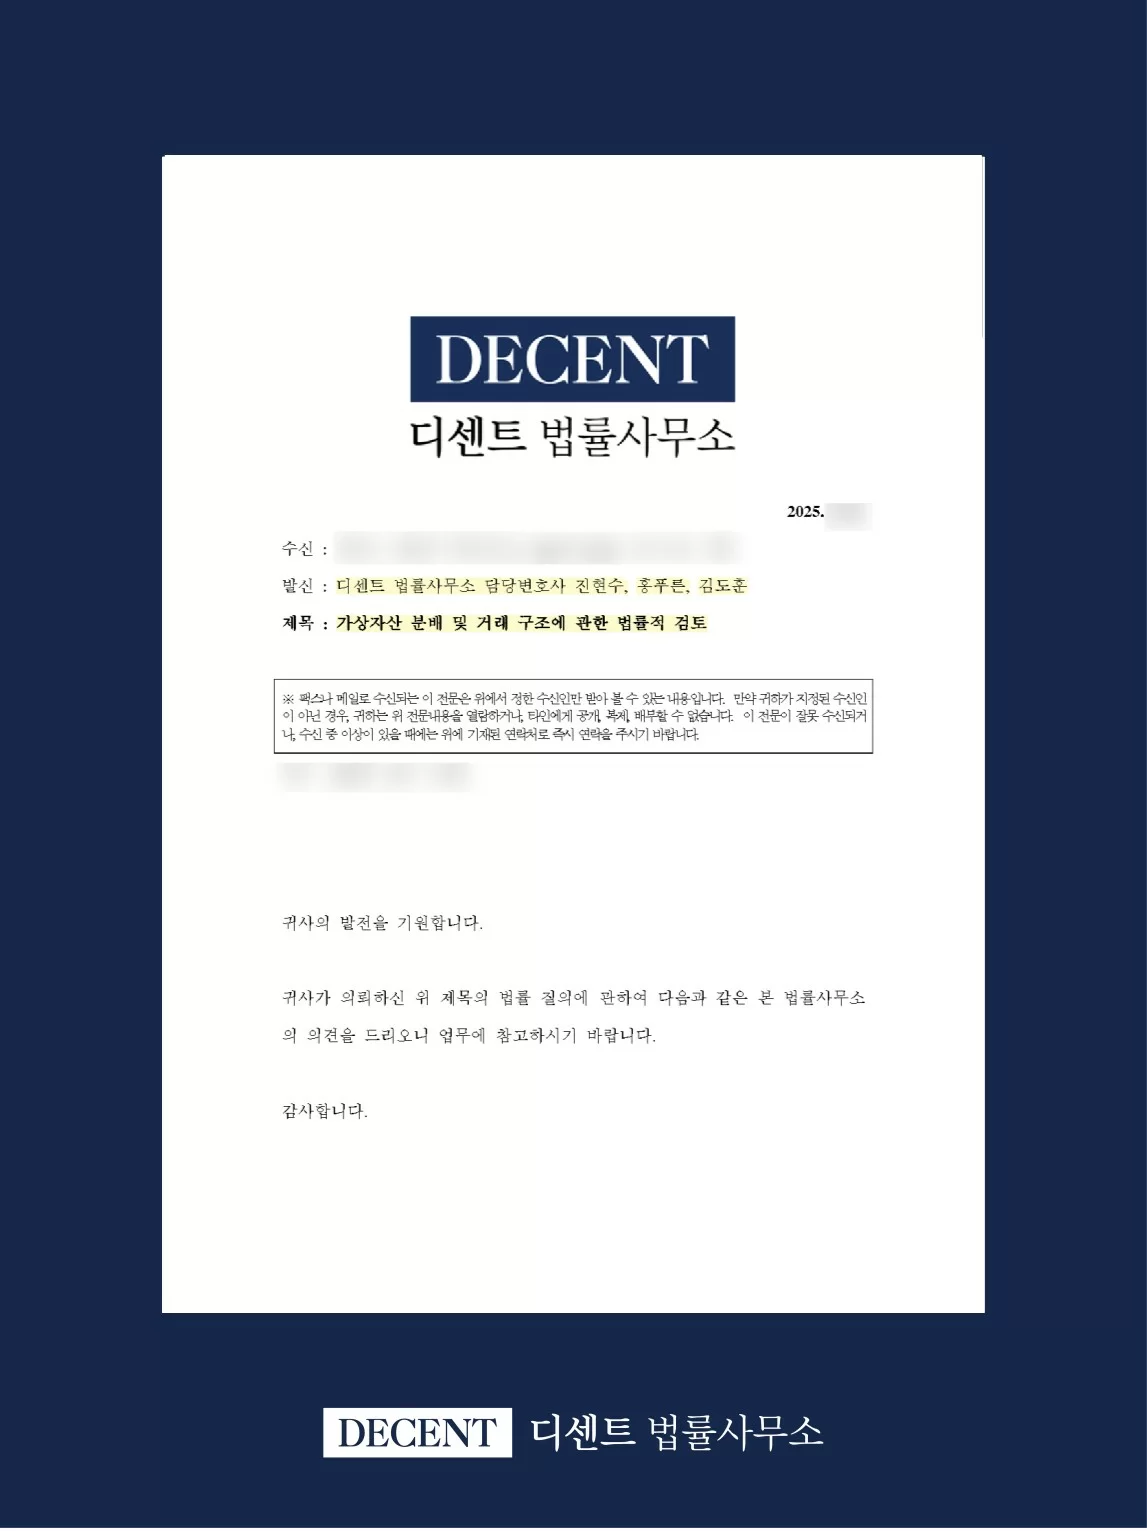
Through this advisory, the client gained a clear understanding of the legal and tax risks across each distribution route, and established a compliant operational foundation through escrow structure design and systematic documentation.
Web3 and NFT businesses operate in a space where the existing legal framework has not yet fully caught up.
The moment the boundary between a personal wallet and corporate assets becomes unclear, compounding risks — from piercing of the corporate veil to double taxation — can materialize all at once.
Resolving problems after a transaction has already occurred is significantly harder than preventing them.
Structure your operations correctly from the start.
If you need help designing an NFT or virtual asset distribution structure, documenting transaction flows, or establishing tax treatment guidelines, contact Decent Law Firm's Virtual Asset Practice.
법률상담 안내
모든 상담은 담당 변호사의 사건 검토를 거쳐 진행됩니다.
사건의 주요 내용을 미리 남겨주시면 보다 구체적인 상담을 받으실 수 있습니다.
담당 변호사
대한변호사협회 등록 변호사가
직접 수행 · 검토한 실제 업무사례입니다.