
USDT Escrow Payment Agency Agreement Review and Advisory on Payment Structure
Case Overview
- Client Information
- Corporate / Business Entity
- Case Details
-
The client planned to pay development fees to an overseas developer using USDT. Under the proposed structure, the USDT would be transferred to a third-party payment agent, which would convert or liquidate the virtual assets into Korean won and deliver the payment to the developer.
The arrangement was structured as a separate ancillary agreement limited to the custody and payment of funds, rather than as part of the underlying development agreement.
Before entering into the agreement, the client requested a legal review of the payment agent’s regulatory status and the potential risks arising from the conversion and payment process under Korean law.
Decent's Strategy
▪️Scope of the Payment Agent’s Role
We examined whether the payment agent’s obligations were clearly limited to holding the funds and converting and transferring them upon satisfaction of the agreed payment conditions.
We also reviewed whether the agreement properly excluded the payment agent from liability for disputes arising under the underlying development agreement.
▪️Potential Classification as a Virtual Asset Service Provider
We reviewed the proposed arrangement in connection with Article 7 of Korea’s Act on Reporting and Using Specified Financial Transaction Information and the Virtual Asset User Protection Act.
Where a business repeatedly or commercially holds, converts, or transfers virtual assets on behalf of third parties, such activities may raise issues concerning registration as a virtual asset service provider.
Accordingly, the payment agent’s actual operating model, transaction frequency, and transaction volume were examined to assess its potential regulatory status.
▪️Allocation of Conversion and Exchange-Rate Risks
We reviewed the contractual provisions governing the conversion rate, applicable fees, exchange-rate calculation method, and the allocation of any shortfall arising during the liquidation process.
The review also covered:
• The liability structure applicable where the payment agent fails to provide timely notice
• The method for calculating the return of deposited funds
• Liability caps for conversion-related shortfalls
• Default interest applicable to delayed payments or refunds
▪️Revision of Contractual Provisions
Based on the review, Decent Law Firm advised the client to include detailed provisions addressing the verification of the payment agent’s regulatory status and the allocation of risks arising from the conversion and payment process.
Results & Significance
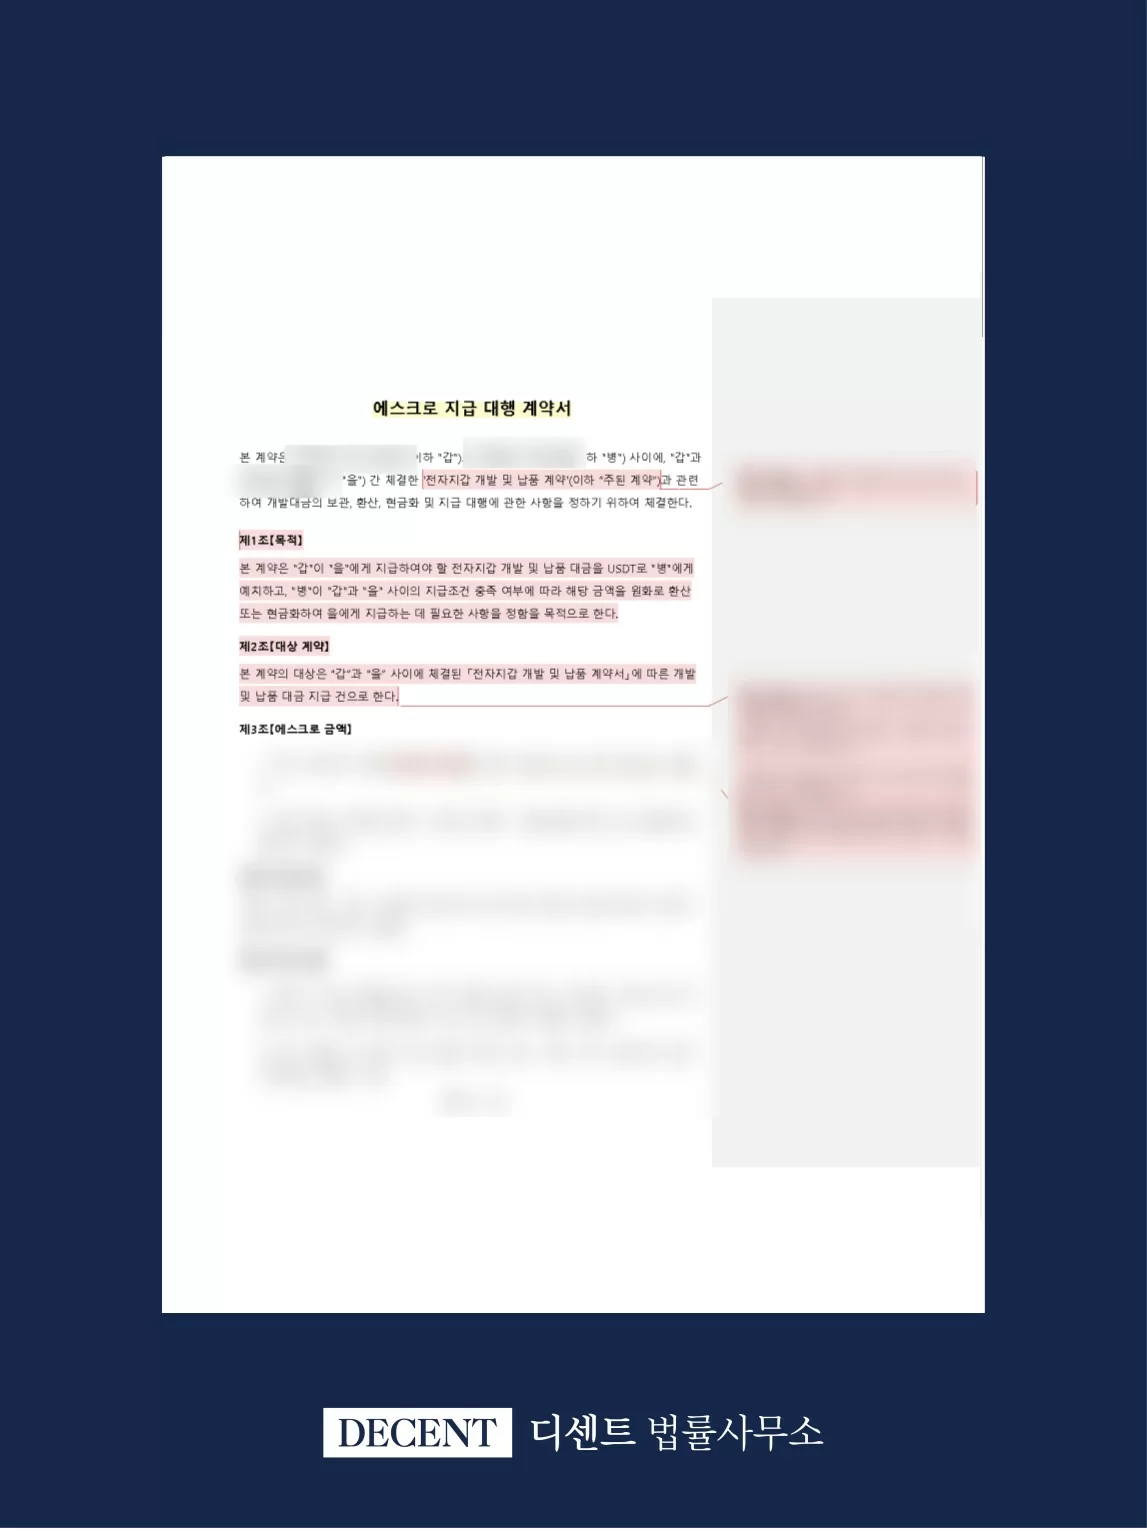
The reviewed agreement clearly defined the payment agent’s limited role in holding, converting, and transferring the USDT payment.
It also clarified the allocation of exchange-rate, fee, shortfall, notification, refund, and delay risks between the parties.
As a result, the client completed the contractual review and received legal advice after assessing the principal regulatory risks associated with the proposed payment structure.
Legal Consultation
All consultations are conducted after a case review by the attorney in charge.
Providing the key details of your case in advance will help you receive more specific advice.